Fiduciary 401(k) Advisor · Plan Design · Benchmarking · Milwaukee & Waukesha, WI
The 401(k) Financial Advisor for Business Owners Who Want More Than a Standardized Plan
Most small business 401(k) plans are bundled, commoditized products with no real advice attached. Milwaukee 401(k) Plans brings fiduciary-based 401(k) plan design, protection for plan sponsors, and one-on-one guidance for your employees — so your plan becomes a competitive advantage, not an administrative burden.
Fiduciary
Led by a licensed Investment Adviser Representative
Advice-First
Planning, not products
Licensed
Advisors who can render real advice
Waukesha, WI
Serving Milwaukee-area companies and beyond
The Problem With Most Company 401(k) Plans
Why most small business 401(k) plans fall short — for owners and employees
The 401(k) market is commoditized — plans are often sold as a bundle with payroll, and the design is an afterthought. When an employee has a question, there's no 401(k) advisor, just a website. And as the plan sponsor, you're carrying fiduciary responsibilities most providers never mention.
As a 401(k) fiduciary, you may be personally liable
If you offer a plan, you're likely a fiduciary under ERISA — and a fiduciary can be held personally liable for neglected duties. Most owners assume their advisor has this covered. Often, no one does.
You're wearing too many hats
ERISA, DOL and IRS rules weren't meant to be a side job. Overseeing the plan pulls you and your team away from running the business.
Your employees ride every market drop
Most participants are stuck in buy-and-hold with no defensive option. Worried employees are distracted employees — and they participate less.
401(k) Plan Design & Advisory Services
5 ways 401(k) plan design can make your plan a real win-win
Every company offers a plan for different reasons — recruiting and retention, higher contributions for owners and key people, tax optimization, fiduciary protection. We design around yours.
Proper Retirement Plan Design
Your content goes here. Edit or remove this text inline or in the module Content settings. You can also style every aspect of this content in the module Design settings and even apply custom CSS to this text in the module Advanced settings.
Lessen Your Administrative Burden
Wear fewer hats. We help position your plan to function effectively so you can stay focused on your top priorities.
Increase Employee Engagement
Individualized planning meetings with licensed advisors — at no incremental cost to your employees — covering financial matters well beyond the 401(k).
Tactical Management for Employee Accounts
A defensive strategy for employee accounts — the kind of management usually reserved for affluent investors — to help navigate periods of uncertainty.
Protect Yourself From Fiduciary Exposure
Help alleviate exposures for the business owner, trustee, or committee — a layer of protection missing from most plans today.
Free 401(k) Benchmarking Report
Been 2+ years since your last 401(k) plan review? You're overdue.
The DOL expects plans to be reviewed at least every 3 years. Our report uses public filings — no work for your team — and flags red flags, fees, and how you compare to plans of similar size. It takes about 30 minutes.
How It Works
How we work with plan sponsors: a simple, no-pressure path to a better plan
Complimentary Conversation
A 30-minute call to understand why you offer a plan, what's working, and where the blind spots might be.
Benchmark & Review
We pull your plan's public filings and deliver a benchmarking report — investments, fees, compliance, and comparison to peer plans.
Design & Implement
If it makes sense, we tailor the plan design, add protection and tactical options, and begin one-on-one meetings with your employees.
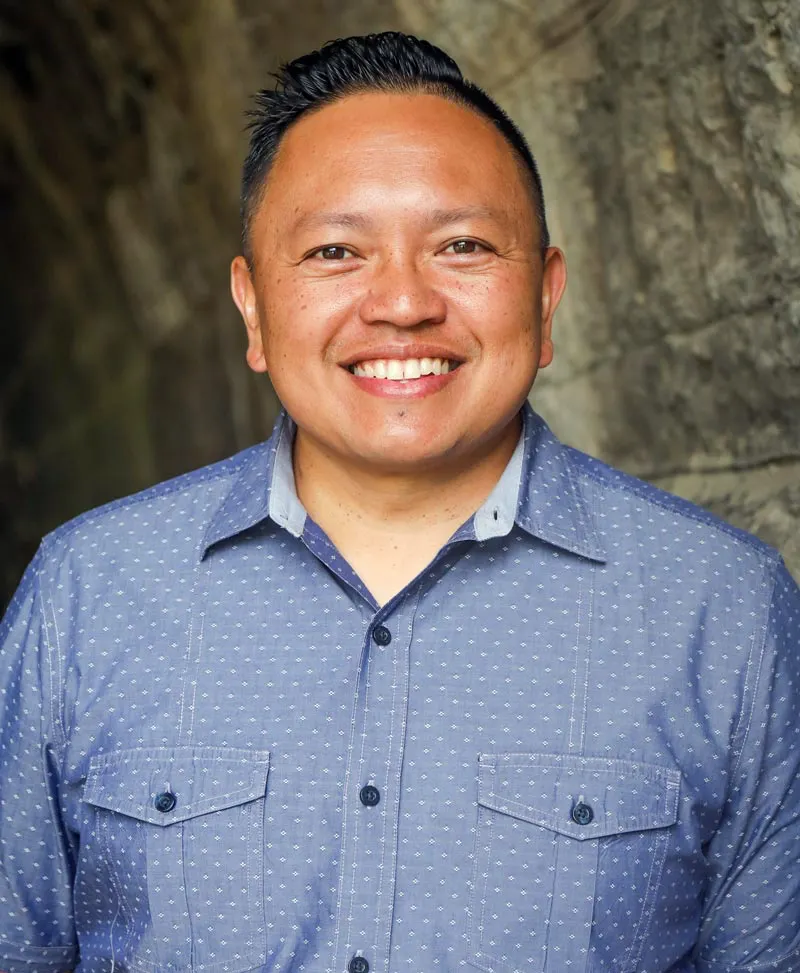
The Advisor Behind Milwaukee 401(k) Plans
Chad Albano, 401(k) Advisor in Milwaukee & Waukesha
Lead Advisor, Milwaukee 401(k) Plans · Fiduciary Retirement Plan Advisor
Chad brings a background in corporate finance and accounting to retirement plan advisory work — which means he speaks the language of owners, CFOs, and leadership teams. He takes a comprehensive-planning, fiduciary approach: the more complex the need, the more value real advice can deliver.
Beyond 401(k)s, Chad also helps with advanced strategies like Non-Qualified solutions to help retain key employees.
Investment Advisor Representative | Corporate Finance Background
Connect with Chad on LinkedIn
Free 401(k) Self-Assessment
How does your plan really stack up?
Answer a few quick questions about plan design, fiduciary oversight, employee engagement, and investment options. Get an instant read on where you're strong and where you're exposed.
Takes about 3 minutes
Plan design fit
Fiduciary exposure
Participation & engagement
Common Questions
Questions 401(k) plan sponsors ask us
Don't see yours? Bring it to the complimentary conversation.
What are a 401(k) plan sponsor's fiduciary responsibilities?
If your company offers a 401(k), you’re almost certainly a fiduciary under ERISA — whether anyone told you or not. That means you’re responsible for running the plan in the best interest of participants, selecting and monitoring your service providers and investment options, keeping fees reasonable, and properly communicating with employees. A fiduciary can be held personally liable for duties that get neglected. Most owners assume their advisor or recordkeeper has this covered. Often, no one does — and that’s the gap we help close.
What does a 401(k) financial advisor do for a company?
A real 401(k) advisor does far more than pick a fund lineup. We help you design the plan around your company’s goals (recruiting, retention, owner contributions, tax efficiency), reduce your fiduciary exposure, benchmark fees and investments against similar plans, and — the part most plans skip — sit down one-on-one with your employees to give actual advice. Because we’re licensed fiduciary advisors, we can render advice, not just point your people to a website.
What is a 3(38) fiduciary, and do we need one?
A 3(38) investment manager is an advisor who takes on discretionary responsibility for selecting and monitoring your plan’s investments — and with it, the fiduciary liability for those decisions. A 3(21) advisor, by contrast, makes recommendations but leaves the final call (and the liability) with you. Which structure is right depends on your plan size, your committee’s bandwidth, and how much risk you want to carry personally. We’ll walk you through both and help you decide what fits.
What is 401(k) benchmarking, and what does the report cost?
Benchmarking compares your plan’s fees, investment performance, and design against plans of similar size and industry — and flags red flags before the Department of Labor does. The DOL expects plans to be reviewed at least every three years (sooner if your headcount, revenue, or workforce has changed). Our benchmarking report is complimentary. It’s built from your plan’s public filings, so there’s no work for your team, and the review conversation takes about 30 minutes.
Do we have to change 401(k) providers to work with you?
Not necessarily. Many of the improvements we make — plan design, fiduciary protection, employee education, and one-on-one advice — can be layered onto your existing plan. In some cases, after a benchmark, it becomes clear that a different recordkeeper or investment platform would serve you better, and we’ll tell you plainly if that’s the case. But the first step is always a review, not a switch.
Let's Schedule a Complimentary Conversation
Talk with a Milwaukee 401(k) advisor. 30 minutes could change what your plan does for your company.
No obligation, no sales pitch. We'll talk through your goals for the plan and tell you plainly whether there's an opportunity to make it better.